
Dow Jones Forecast: DJIA rebounds as Trump seeks exit plan as mixed messaging continues
US stocks are set to open higher on Tuesday as markets respond positively to another report suggesting possible de-escalation in the Middle East, offering some hope of stability after a bruising month for risk assets.
Written by
Fiona Cincotta
Senior Market Analyst
US futures
Dow futures 1.2%, S&P futures 1.2% & Nasdaq futures 1.2%
In Europe
FTSE 1.2% & DAX 1.3%
- US stocks rise as Trump hints at the end of the war
- The Strait of Hormuz remains effectively closed
- US JOLTS job openings are due shortly
- Oil rises and is set for a record monthly gain
US stocks rise, but the Strait remains closed
US stocks are set to open higher on Tuesday as markets respond positively to another report suggesting possible de-escalation in the Middle East, offering some hope of stability after a bruising month for risk assets.
According to the Wall Street Journal, President Trump is reportedly open to ending the conflict with Iran even if the Strait of Hormuz remains only partially reopened.
However, the market response remains cautious. Those comments come as the US continues to deploy additional troops to the region, reinforcing the sense that geopolitical messaging remains mixed and that the risk of renewed escalation is still very much alive.
That is important because even if outright military tensions ease, the economic damage from elevated oil prices may already be feeding through. With oil still above $100 a barrel, higher energy costs are likely to tighten financial conditions, raise inflation pressures, and weigh on growth.
Attention will also turn towards the US economic calendar. JOLTS job openings are due later today and are expected to show a decline to 6.92 million, which could offer another clue on the health of the labour market.
Remarks from Fed Governor Michelle Bowman and Chicago Fed President Austan Goolsbee will also be in focus.
Their comments follow remarks from Fed Chair Jerome Powell, who said inflation expectations remain well anchored, suggesting the Fed can afford to wait and assess the impact of the conflict before responding. That helped calm some inflation fears and pulled Treasury yields lower.
Markets are now pricing in only around a 5% chance of a Fed rate hike this year, down from around 25% previously.
Even so, gold is on track for a bruising month, down around 11% in March, as it has failed to attract sustained safe-haven demand and has instead come under pressure from previously rising Treasury yields and a stronger US dollar.
Corporate news
Big Tech is benefiting from the modest improvement in risk sentiment. Stocks such as Meta, Microsoft, Apple, and NVIDIA, which had come under pressure in recent sessions, are showing signs of stabilising and moving higher.
McCormick is rising more than 3% after reports that Unilever is in talks with the spice maker over a potential merger. The proposed deal would reportedly include an upfront cash component of $15.7 billion, with Unilever and its shareholders expected to hold 65% of the combined company upon completion.
Dow Jones – technical analysis
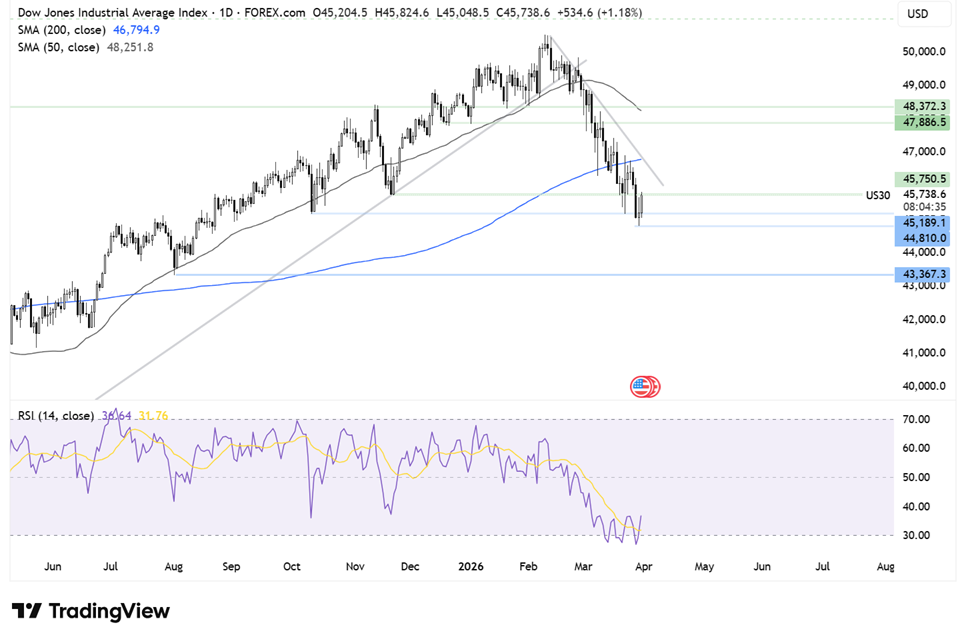
After falling to a low of 44,810, the Dow Jones has rebounded and is now testing resistance at 45,700, which marks the November 2025 low.
Buyers may take encouragement from the recent hammer candlestick formation, but a sustained move above 45,700 is needed to improve the near-term picture.
A break higher would expose the 200-day SMA at 46,750, which also broadly aligns with the falling trendline resistance. A move above that area would suggest the index is regaining firmer footing.
On the downside, failure to clear 45,700 could leave the rebound vulnerable. Sellers would need to break below 44,810 to confirm a lower low and extend the broader bearish move.
FX markets – USD eases, GBP/USD rises
The US dollar is easing modestly, although it remains on track for its strongest monthly gain since July last year, having benefited from safe-haven demand during the Middle East conflict and from elevated oil prices.
The broader macro logic remains supportive for the dollar: markets continue to see the US as relatively better positioned than many other major economies to absorb an energy shock.
EUR/USD is edging lower after eurozone inflation came in softer than expected, even though it still posted its largest jump since 2022.
Consumer prices rose 2.5% year-on-year in March, up from 1.9% in February and the highest level since January 2025, but below the 2.8% expected. More importantly, core inflation unexpectedly slowed to 2.3%, while services inflation also eased.
That may make it harder for the ECB to validate the full extent of the hawkish repricing currently seen in rates markets, although investors still expect two to three ECB rate hikes this year.
GBP/USD is rising modestly as the dollar softens and investors digest mixed UK data.
UK GDP rose just 0.1% quarter-on-quarter, reinforcing the view that the economy was already stagnating even before the Iran conflict began.
At the same time, BRC shop price inflation rose to 1.2% year-on-year from 1.1%, suggesting that higher costs linked to the conflict are starting to feed into the domestic economy.
Oil set for a record monthly gain
Oil prices are rising again on Tuesday, with Brent on course for its largest monthly gain on record, as investors continue to weigh the possibility of a diplomatic breakthrough against the risk of a prolonged disruption to global energy supply.
Despite more constructive comments from Trump today, they come just a day after he reiterated threats against Iran’s energy infrastructure if Tehran failed to reopen the Strait of Hormuz.
That contradiction is key. Diplomatic signals remain mixed, and as long as uncertainty persists and shipping disruptions remain in place, oil prices are likely to stay elevated.
For now, the market is not yet prepared to price in a sustained easing in energy risk.
Latest market news
Web Trader platform
Our sophisticated web-based platform is packed with features.
Open an account today
Experience award-winning platforms with fast and secure execution.
Economic calendar
Related articles
Nasdaq 100 Forecast: NDX slips ahead of Fed Chair Warsh’s speech
U.S. stocks are edging lower on Friday, giving back some of yesterday's gains after Nvidia's strong outlook revived the tech trade. The focus has now shifted firmly to Fed Chair Kevin Warsh's Jackson Hole speech, with investors looking for more clarity on the outlook for interest rates.

S&P 500 Forecast: SPX after Nvidia revives confidence in the AI trade
U.S. stocks are heading higher on Thursday, with technology leading the move after Nvidia's stronger-than-expected outlook revived confidence in the AI trade.

Oil, EUR/USD Forecast: Two trades to watch 2608
Oil falls further on diplomatic hopes for a Middle East resolution. EUR/USD consolidates ahead of U.S. inflation and Jackson Hole.